Quick answer
Wealth and debt both compound from the same source: hundreds of small, repeated financial habits, not one dramatic decision. Get one percent better each day, checking a rate, paying down a balance, and gains compound to roughly 37 times better over a year. Get one percent worse each day and the decline compounds just as fast in the other direction. The two highest-leverage habits to build are auditing what a savings account actually earns against competitive options, and checking whether a credit card balance is being paid down or just serviced. Neither is a one-time decision; both are renewed silently every day they go unchecked. You should treat both as a recurring habit, not an annual chore. Run your specific accounts through the SwitchWize Money Map to see what your own habits are quietly costing or earning you. Understanding how financial habits compound is the first step toward building wealth that accelerates rather than erodes.
- Wealth isn't built or eroded by one big decision, it's built by hundreds of small, ordinary ones repeated so consistently that nobody notices them happening, the same compounding logic behind James Clear's Atomic Habits.
- Get one percent better each day and gains compound to roughly 37 times better in a year. Get one percent worse each day and the decline compounds just as fast, collapsing rather than eroding gently.
- A savings account earning far less than competitive options, or a credit card balance carried month to month, aren't one-time decisions. They're habits renewed silently every day they go unchecked.
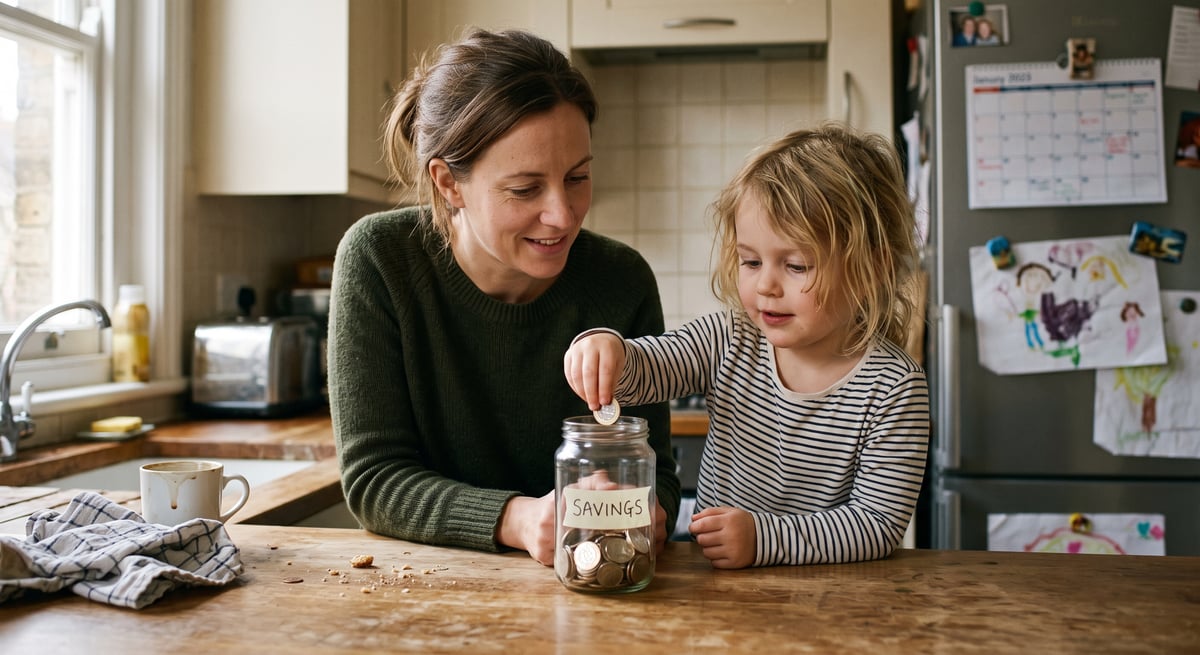
Watch a child drop a single coin into a jar labeled savings and it looks like nothing. It is nothing, financially speaking: one coin, a few cents. But the habit behind that moment, repeated for years, is close to the entire difference between a family that builds wealth and one that doesn't.
In twenty-five years of working inside financial institutions, I've watched thousands of people make decisions about their money. Almost none of those decisions were made in a single, dramatic moment. Sure, there are the occasional home runs: a well-timed bet, a windfall, a lucky break. But in almost every instance, wealth isn't built or eroded by one big choice. It's built by hundreds of small, ordinary ones, repeated so often that nobody noticed them happening at all.
That idea is the entire premise of James Clear's Atomic Habits, one of the most widely read books on behavior change in the last decade. Clear's central argument is simple: small, consistent actions compound over time into results far larger than they appear to warrant in the moment. Get one percent better every day, and by the end of a year you're not 365 percent better. You're roughly 37 times better, because gains compound on themselves. The reverse is just as true. A one percent decline each day, repeated, doesn't erode your position gently. It collapses it. The book's real insight isn't that habits matter. Most of us already suspect that. It's that the trajectory set by your daily habits matters more than any single decision you'll ever make.
Financial hygiene works exactly the same way.
Alan Greenspan spent years warning that inadequate financial literacy was one of the deepest risks facing ordinary consumers, well before the 2008 crisis made the case for him more forcefully than any speech could. Two decades later, his warning holds up uncomfortably well. Most of us were never taught to think about our money as a system of habits. We were taught to think about it as a series of one-off events: get a raise, open an account, apply for a card, refinance a mortgage. But the accounts sit there for years. The debt compounds every month. The habits, good or bad, are what actually determine where you end up.
The habits hiding in plain sight
Consider a few examples. Your savings account is effectively in the market every single day: the rate it pays relative to what's available elsewhere shifts constantly, which means the decision to leave money parked where it is isn't really a one-time decision at all. It's a habit, renewed silently every day you don't check it, and it deserves scrutiny at something close to that same frequency. Money sitting in an account earning a fraction of a percent, while competitive options elsewhere pay meaningfully more, is a habit of inertia quietly compounding against you.
Credit card debt works the same way, only more urgently. Carrying a balance isn't a decision you make once when you swipe the card. It's a decision you're implicitly remaking every single day that balance sits there, accruing interest against you at a rate that's usually far worse than anything a savings account is losing on the other side. It deserves to be reexamined daily, not filed away and revisited once a year. Neither of these habits announces itself as a crisis. That's precisely what makes them dangerous. They're small, boring, and easy to ignore, until you look up a year or two later and realize how much they've quietly cost you.
I'd argue that after the habits that protect your physical health, few habits shape a person's life, and their family's life, as profoundly as financial ones. The gap between the household that develops good financial habits early and the one that doesn't isn't just about this year's numbers. It compounds across a lifetime, and often across generations, shaping the opportunities available to children and grandchildren who never made a single one of the original decisions.
Why this is the job
This is precisely why SwitchWize exists. Our job is threefold: show you the full, honest landscape of competitive options across savings, credit, and lending, because you can't build a good habit around a choice you don't know you have. Give you clear, timely education, so those choices actually make sense. And, most importantly, help you build the habit of checking in on your own financial hygiene, regularly, deliberately, without judgment, the same way you might build a habit around exercise or diet.
None of this requires a dramatic overhaul of your financial life. So here's the exhortation, plain and simple: take a page from Atomic Habits and look honestly at your own financial environment. Ask what habits it's currently reinforcing, the good ones and the quietly costly ones, and decide, deliberately, which ones you want to build instead. Then act on it, in whatever small measure you can manage today. That's the whole method. Small actions, repeated daily, throw off outsized rewards over time. It's true of your health. It's true of your career. And it's every bit as true of your money.
A simple audit anyone can run this week
The audit itself does not need to be complicated, which is precisely why it works as a habit rather than a project. As of 2026, the best nationally available high-yield savings accounts are paying 4.20% APY, a useful benchmark against whatever your own account is currently earning. If the gap between the two is meaningful, that gap is a habit of inertia, not a one-time decision you made and can forget about. A quick rule of thumb: if your savings rate is more than half a point below the nationally available best rate, the audit has already paid for the five minutes it took.
Savings rates move with the broader rate environment, which is exactly why a once-a-year check misses more than a monthly one:
The same applies on the debt side. If a credit card statement shows a balance carried for a second consecutive month, that is the moment to check whether the budget behind it needs adjusting, not just the payment.
Which Habit to Build First
- Move
- Move the balance and set a monthly reminder to recheck it, so the new rate does not quietly go stale too
- Move
- Build a habit of paying above the minimum every cycle, not just when it feels urgent
- Move
- Start with one account and one card; a habit that covers everything on day one usually does not survive week two
- Move
- Run it through the compound interest calculator rather than estimating
Sources
Habit-formation timelines referenced above come from University College London's original research (Lally et al., 2009, published in the European Journal of Social Psychology). General guidance on building consumer financial habits and account comparison is also covered by the CFPB's financial education resources (ConsumerFinance.gov). Household financial-capability patterns, including how few small habits compound into large gaps, are also documented in the Federal Reserve's own consumer research (FederalReserve.gov).
What to Do Now
Frequently Asked Questions
Why do small financial habits matter more than big financial decisions?
How long does it take to build a new financial habit?
What's the highest-leverage financial habit to start with?
What should I do after reading The Compounding Power of Financial Habits?
The 5-minute money briefing
One email per week. New rates, fed moves, and what to actually do about them.
No spam. Unsubscribe anytime.
Answer a few questions about your situation and goals. Money Map points you to the highest-value next step across savings, mortgage, cards, and debt.
Editorial review
What changed since the last update
Was this guide helpful?
Found an inaccurate, outdated, or missing claim? Report a correction. We verify reports against the relevant source before changing a guide or ranking.
Adeesh Setya is Head of Financial Research & Principal at SwitchWize, with 25+ years of experience in deposits, treasury management, banking products, and financial services. He previously served as Treasurer at Merrill Lynch Bank USA and Morgan Stanley Bank USA, where he managed bank funding, deposits, and interest-rate risk. He writes on Federal Reserve policy, the general marketplace for banking products, and what they mean for savers and consumers.
Available for on-record interviews, background briefings, and custom data cuts.
research@switchwize.com