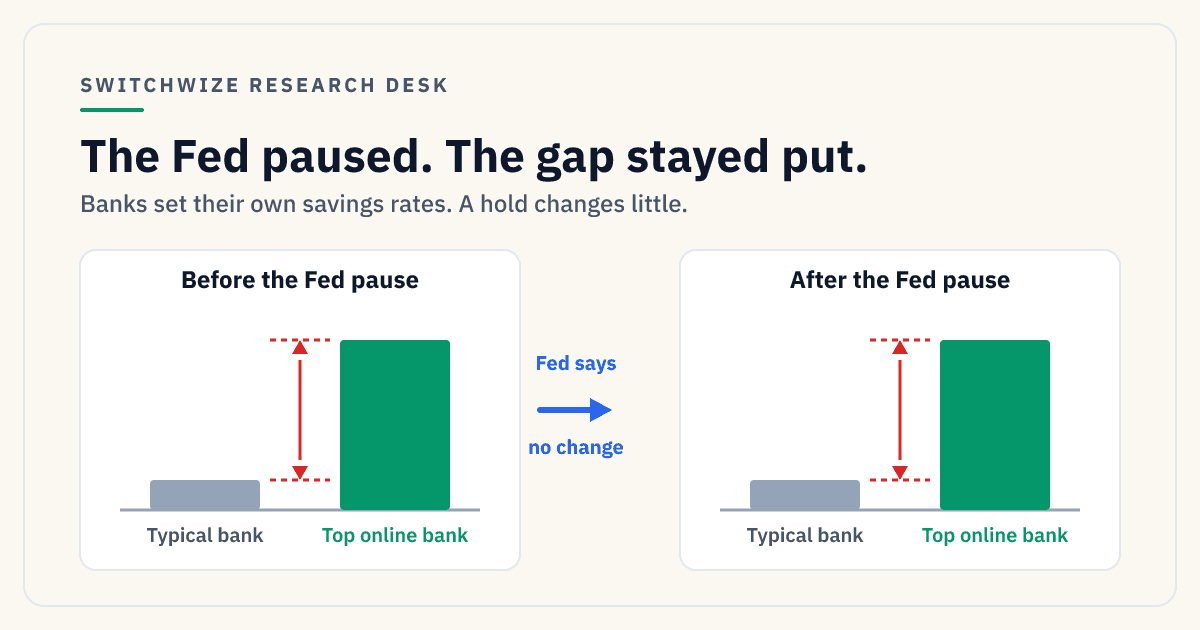
- The Fed held its target range at 3.50%-3.75% on July 29, 2026, its fifth straight hold, with three members preferring a hike instead.
- The FDIC's national average savings rate has sat near 0.38% APY since at least May 2026 and stayed there through the pause, while top online savings accounts kept paying above 4%.
- The gap between average and top savings rates is a bank pricing decision, not a Fed outcome, which is why it didn't move around the July announcement and hasn't closed on its own for months.
Update, October 25, 2026. The picture is the same, with a higher top rate. The FDIC's national average savings rate was still 0.38% APY on October 19. The best verified savings rate in SwitchWize's approved snapshot was 4.40% APY at PiBank on October 25, up from the 4.25% quoted in the October 1 update below. On $25,000, that is about $1,100 a year against $95 at the national average, a gap of about $1,005. Banks have still been slow to pass on the September hike. On day 39 after it, our Fed Hike Tracker measured 87 savings accounts: 31 had raised their rate, 53 had not changed and 3 had moved lower. The median account passed on none of the hike.
On July 29, 2026, the Federal Reserve did the least dramatic thing a central bank can do: nothing. It held the federal funds target range at 3.50% to 3.75%, its fifth consecutive meeting without a change, and three of its own voting members, Beth Hammack, Neel Kashkari, and Lorie Logan, would have preferred to raise it a quarter point instead. No cut, no cover for banks to quietly trim what they pay savers. For anyone tracking fed pause savings account rates in 2026, that combination is the point: a hold gave banks no reason to change what they pay depositors in either direction.
And yet if you checked your own savings account rate the week after that decision, it almost certainly looked exactly like it did the week before. That's not a coincidence, and it's not really a story about July 29. It's a story about a gap that was already there, stayed there, and mostly ignores the Fed's calendar either way.
What actually happened on July 29
The Fed's own statement was brief: the Committee decided to maintain the target range at 3.50% to 3.75%. Three regional bank presidents, Hammack (Cleveland), Kashkari (Minneapolis), and Logan (Dallas), dissented in favor of a quarter-point increase, a notably hawkish lean for a group that spent most of 2025 debating how fast to cut. The Fed had already lowered rates three times to close out 2025; every one of its five scheduled decisions in 2026 through July has been a hold.
A hold isn't a headline the way a cut or a hike is, but it matters here precisely because of what it doesn't do: it gives banks no fresh room to lower what they pay depositors, and no fresh reason to raise it either. Whatever gap existed between an average bank and a competitive one before July 29 was, mechanically, still going to be there on July 30.
The average didn't move, but it also wasn't going to
The FDIC's own national average savings account rate is a useful check on that logic because it's published monthly and tracks actual bank behavior rather than headlines. It read 0.38% APY in data as of the end of May 2026, and it read 0.38% APY again in data as of the end of July 2026, the same reading spanning the entire run-up to and aftermath of the July FOMC meeting. Bankrate runs its own weekly survey of more than 500 banks and credit unions with a different methodology, and its national average sat at 0.62% APY as of August 21, 2026, still a fraction of what the best accounts pay.
Two different surveys, two different numbers, both far below the top of the market:
- Rate
- 0.38%
- As of
- July 31, 2026 (published Aug. 17)
- Source
- FDIC National Rates and Rate Caps
- Rate
- 0.62%
- As of
- Aug. 21, 2026
- Source
- Bankrate weekly bank survey
- Rate
- 4.10%
- As of
- Aug. 21, 2026
- Source
- Bankrate (CIT Bank)
- Rate
- 4.40%
- As of
- Continuously updated
- Source
- SwitchWize rate observations
Whichever "average" you use, the distance to the top of the market is roughly the same story: several times over, not a rounding error.
Why the gap doesn't track Fed announcements
It's tempting to assume savings rates move like a dial connected directly to the Fed's target range: cut, and every bank's APY drops in lockstep; hold, and nothing changes anywhere. Real bank pricing doesn't work that cleanly, and this July is a fairly clean illustration of why.
Economists describe how much of a Fed rate move a bank passes through to depositors as its deposit beta. A large, branch-heavy bank with millions of customers who rarely shop around has a low deposit beta: it can pay close to nothing because switching, closing an old account, updating direct deposits and autopay, feels like more hassle than it's worth to most of its depositors. An online bank competing for every single deposit has a high deposit beta: it has to pay close to what the rate environment can support, or lose the customer to a competitor a few clicks away.
That structural difference, not the Fed's meeting schedule, is what sets the gap. A hold like July's doesn't test it much, because there was no rate change for either kind of bank to react to. But the same logic explains why the gap didn't meaningfully close during the Fed's three cuts in late 2025 either: low-beta banks had so little room to cut from already-thin rates that top accounts kept paying multiples of the national average through that cycle too. The gap is closer to a fixture of how competitive (or uncompetitive) deposit pricing is at a given bank than it is a live readout of Fed policy.
What the gap is actually worth
On a representative $25,000 balance, at the FDIC's 0.38% national average, that money earns about $95 over a year. At the 4.10% top widely available rate Bankrate reported on August 21, 2026, the same $25,000 would earn about $1,025, a savings opportunity of around $930 a year for making no change to the money itself, only to where it sits. At SwitchWize's tracked best available savings rate today, 4.40%, the same balance would earn roughly … over a year.
SwitchWize tracks that distance every month and calls it the Bank Gap Index: the dollar gap between the national-average savings rate and the top widely available rate, priced on a representative balance. It isn't a Fed metric. It's closer to a scoreboard for how much a saver's own bank is choosing to keep for itself, and the full methodology and monthly history are on its dedicated report.
What this means going forward
None of this is a forecast about the Fed's next move. The Committee could hold again, cut, or, if the three July dissents are any signal, face renewed pressure to raise. What this snapshot does show is that the size of the average-to-top gap isn't something a saver needs to time around a Fed decision. It didn't shrink because the Fed held. It wouldn't have automatically shrunk if the Fed had cut, either, since low-beta banks had little room left to fall from. The gap responds to bank pricing decisions on a much slower, less newsworthy clock than the FOMC's.
That also means there's no reason to wait for a "better moment" tied to a Fed announcement before checking whether your own savings account is one of the low-beta ones. The FDIC insurance on a 0.38% account and a 4%-plus account is identical up to $250,000 per depositor, per bank, per ownership category. The difference between them isn't risk. It's a pricing decision your bank made and is counting on you not to notice.
Update, October 1, 2026: the Fed hiked in September
The snapshot above covers the July 2026 hold. Since then the Fed has moved: on September 16, 2026 it raised the federal funds target range a quarter point to 3.75% to 4.00%, its first hike since 2023, by a 12 to 0 vote. Its September projections show one more hike penciled in for the end of 2026.
Two weeks after that hike, the national average had not budged. As of October 1, 2026, SwitchWize's reading of the national average savings rate was still about 0.38% APY, while its best tracked high-yield savings rate was 4.25% APY (CIT Bank). On $25,000, that is a savings opportunity of about $968 a year. (This October figure uses SwitchWize's own rate data, so it isn't a like-for-like comparison with the Bankrate-based August figure above.)
Two weeks is too soon to judge how much of the hike banks will pass through, and online banks typically move faster than branch-heavy ones. But the early read fits the pattern this piece describes: the gap between an average account and a top one is set by bank pricing, and a Fed move, up or down, doesn't close it on its own.
What to Do Now
Sources
- Federal Reserve, September 16, 2026 FOMC statement, target range raised to 3.75%-4.00% by a 12 to 0 vote (October 1, 2026 update).
- Federal Reserve, July 29, 2026 FOMC statement: target range held at 3.50%-3.75%; Hammack, Kashkari, and Logan dissented in favor of a quarter-point increase.
- FDIC, National Rates and Rate Caps (August 2026): national average savings APY of 0.38%, data as of July 31, 2026.
- FDIC, National Rates and Rate Caps (June 2026): national average savings APY of 0.38%, data as of May 31, 2026, used to establish the rate had not moved across the period.
- Bankrate, Average Savings Account Interest Rates: Bankrate's own weekly-survey national average of 0.62% APY, as of August 21, 2026.
- Bankrate, Best High-Yield Savings Accounts: top advertised APY of 4.10% (CIT Bank), as of August 21, 2026.
This article is educational, not individualized financial advice. Rates change continuously; the SwitchWize figure above updates live, while the FDIC, Bankrate, and Fed figures are dated snapshots as cited, and the October 1, 2026 update uses SwitchWize rate data as of that date and will drift from current conditions over time.